


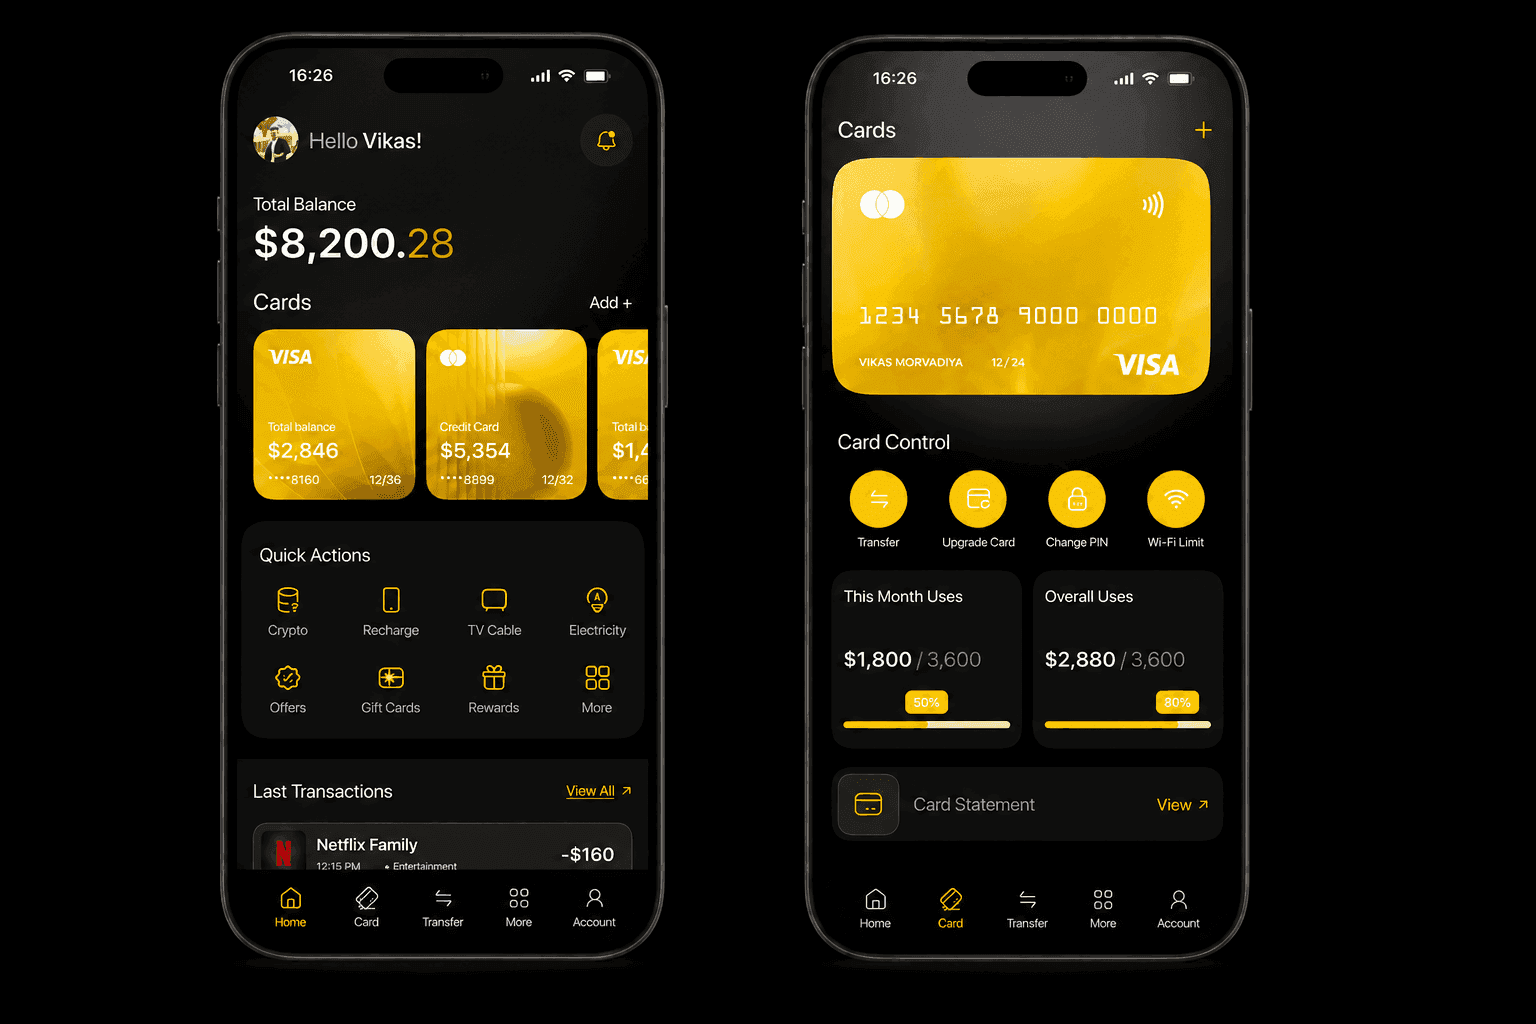
Payment gateway & card issuing
Checkout, settlement and card-issuing infrastructure built around the constraints your product actually operates under, not a generic template.
Industries · Fintech
Payment infrastructure engineered to your compliance team's requirements, not to a generic template. Banks, neobanks, payment rails, lending — built with the controls and records your own reviewers ask for, marketed with the same discipline.
Corum8 builds fintech infrastructure — payment rails, neobank platforms, identity and onboarding pipelines — and runs the investor PR, B2B marketing and executive content that fintech teams need. Your legal and compliance people set the requirements. We build and write to them.
What's included
Checkout, settlement and card-issuing infrastructure built around the constraints your product actually operates under, not a generic template.
Account, ledger and banking-partner integration with the reconciliation and record-keeping your reviewers ask for.
Sumsub, Jumio and Persona pipelines with case management and decision logs, so every onboarding decision has a trail behind it.
Content written to clear your legal review the first time, not rewritten three rounds deep.
Campaigns aimed at specific institutions by name, plus outreach built for the committees that actually sign off on fintech purchases.
Raise-adjacent press and positioning that reads credible to institutional readers, not consumer-brand copy.
Placement in the outlets institutional buyers and investors actually read.
Brand, acquisition and PR for banks and forex brokers, built inside the ad-platform rules from the first draft.
Is this you?
You don't need all of them. One is usually enough to justify the call.
Marketing keeps producing content your reviewers reject three rounds deep — the review needs to happen earlier in the pipeline.
Your team is asking about transaction monitoring and decision history that your current stack simply doesn't record.
Your buying committee is five to twelve people deep, but your marketing motion is built for a single consumer click.
You need investor-grade PR and positioning before the round closes, not a generic press release after.
A new market means new requirements from your own legal team, and both the product and the content need to reflect them.
Financial-services ad restrictions keep flagging your campaigns because the creative wasn't built around them.
Sectors
The constraints differ, the discipline doesn't.
Account and ledger infrastructure with reconciliation built in from the start.
Checkout and settlement infrastructure across multiple corridors.
Underwriting-adjacent infrastructure with careful data handling.
Insurance product infrastructure and the customer content that goes with it.
Onboarding and transaction-monitoring pipelines that keep a full decision record.
Campaigns built for named institutions and the committees that sign off on them.
Consumer and institutional trading products with the UX serious traders expect.
Brand, acquisition and PR for banks and forex brokers, built inside the ad-platform rules.
Process
We start by getting your legal and compliance people in the room to tell us what the product and the content have to satisfy, and who the buyer actually is.
Payment, onboarding or lending infrastructure engineered against that map rather than bolted onto it afterwards.
PR, executive content and paid creative written to get through your legal review the first time.
Content, named-company campaigns and paid acquisition all working inside those constraints from week one, rather than discovering them later.
Case studies
A neobank launch and an InsurTech content library, both built alongside the review process rather than ahead of it.
A neobank team needed banking-partner integration and account infrastructure, launched alongside brand and content that wouldn't stall in review. Building the ledger architecture and the launch messaging in parallel meant the engineering constraints shaped the messaging while it was still being drafted, rather than forcing a rewrite after the fact.
An InsurTech platform needed a content library — policy explainers, disclosures, marketing copy — that wouldn't take three rounds of rewrites. We built the review step into the content pipeline itself rather than treating it as a final gate, so the reviewers were shaping the material as it was written instead of sending it back afterwards.
Why Corum8
Legal review happens during content and product creation, not as a final gate that sends everything back.
Reconciliation, decision logs and transaction records designed to be examined closely, because in this category they will be.
Campaigns and content built for the committees that actually approve fintech purchases, not for a generic job title.
Business-press caliber placement, not consumer-brand press-release volume.
The same engagement covers the infrastructure and the content that has to clear the same review.
10+ years building in this category, so the constraints your team works under aren't new to us.
What drives scope
Cost is driven by product surface, buyer type and content-review depth.
A payment gateway, a neobank and a lending platform each carry different engineering and UX implications.
One market is one build. Multi-region coverage with localised content and per-market requirements is heavier.
Consumer-facing fintech marketing differs meaningfully from institutional B2B marketing aimed at five-to-twelve-person buying committees.
Light disclosure content is one scope. A full reviewed content library across every claim you make is materially more.
Banking partners, card processors, identity providers and ledger systems each add integration and testing work.
Ongoing investor PR ahead of a raise requires sustained positioning work beyond a single press cycle.
FAQ
A serious fintech agency builds financial infrastructure — payments, banking, identity and onboarding — and runs the PR, B2B marketing and content that clear legal review, rather than applying generic startup marketing to a financial product. The discipline is treating your review requirements as an input to both the engineering and the content, not a final gate either has to pass through separately. We build and write. Your legal and compliance teams decide what satisfies their obligations.
Cost is driven by product surface, geographic coverage, buyer type, content-review depth, integration count and investor-relations intensity. A single-market consumer product is a different budget than a multi-region institutional platform with a full reviewed content library. The biggest single swing is usually integration count — every banking partner, card processor and identity provider is its own build and its own test surface.
Yes — we integrate identity providers like Sumsub, Jumio and Persona with transaction-monitoring pipelines and case-management systems that keep a full decision record. That record gets architected into the data model directly rather than added as an afterthought, because retrofitting a decision history onto a system that never captured one is painful. What those controls need to satisfy is set by your compliance team, not by us.
Yes — and the marketing motion differs significantly. Consumer fintech needs performance ads and brand content built inside the ad platforms' financial-services restrictions; institutional fintech needs campaigns aimed at named institutions and content senior enough for the committee that signs off. We scope the right motion to the actual buyer rather than running one playbook at both.
Infrastructure (payments, banking, lending or onboarding), reviewed content, B2B or consumer marketing matched to the buyer, investor and analyst PR, and paid acquisition built inside the ad platforms' financial-services rules. Engagements scope to what the specific product and market actually require. Not every team needs all of it, and we would rather scope down than sell you a bundle.
By building the review step into the content pipeline itself, not treating it as a final approval gate. Financial products carry real restrictions on what you can say — guaranteed returns, advice language, risk framing. Your legal team knows which apply to you. We get those constraints from them before the first draft, write against them, and route the material back through review while it's still cheap to change.
Yes — investor and analyst PR ahead of and around a fundraise is part of the practice, positioned for institutional readers rather than consumer-brand press coverage. This works best started before the round closes, so the market narrative is already in place when the raise is announced. We run the press programme. We don't make claims about what a round will or won't achieve.
We scope to whatever is blocking you now, and expand only when it earns it. For some teams that is the infrastructure; for others it is the content and press programme; often it is both, because the product and the claims about it have to clear the same review. If what you need is genuinely one integration or one placement, we will scope exactly that. The combined engagement earns its value when product and story move together, and we will tell you which situation you are in up front.